Property Assessments
Comprehensive roof and building evaluations with detailed photos, reports, and system analysis. Independent inspection before the carrier scope is accepted.
Arizona|Colorado|Texas|Oklahoma|Nationwide Response Available|No Recovery, No Fee
Denali Loss Consulting • Licensed — Arizona · Colorado · Texas · Oklahoma · Louisiana
Expert guidance, detailed documentation, and strategic advocacy to help property owners and managers protect their assets and achieve the results they're entitled to under their insurance policies. Nationwide response available.
We work for you, the policyholder — not the insurance carrier.
"You're Not Alone"
Track 1 — Proactive
When a public adjuster is engaged from the first notice of loss, claims resolve faster, documentation is stronger, and the carrier has less room to erode your settlement. Denali establishes an independent damage record before the carrier adjusts — setting the evidentiary foundation that drives every negotiation that follows.
Faster resolution. Stronger documentation. A claim the carrier cannot easily erode.
Track 2 — Recovery
A low settlement number is not always the final word. When a commercial claim has been underpaid, denied, or delayed without sufficient justification, Denali reviews the carrier's scope, the policy's coverage grants, and the full damage record — and builds the case for a fair settlement.
We build the case. Then we fight for the number your policy supports.
What We Do
Comprehensive roof and building evaluations with detailed photos, reports, and system analysis. Independent inspection before the carrier scope is accepted.
Policy review, claim documentation, and advocacy for fair negotiations. We prepare and present supplement submissions with evidence the carrier must address.
Identify issues early, prioritize repairs, and extend the life of your assets. Proactive documentation strategy to protect claim rights before a loss event.
Clear communication, fast response, and solutions focused on your portfolio goals. We work alongside property managers and asset owners as a true partner.
Storm, hail, wind, and complex property claims across commercial, industrial, and multifamily assets. Appraisal and dispute support when carrier negotiations stall.
The Data Says
Regulatory catastrophe data from Florida's Office of Insurance Regulation — the most detailed commercial claims dataset available in the U.S.
56,751
Commercial property claims across Hurricanes Helene & Milton
Florida OIR Catastrophe Data
46.9%
No reported payment at regulatory reporting date
26,636 of 56,751 claims
#1
Claim-handling complaints are the top category in NAIC data
National Assoc. of Insurance Commissioners
Arizona — October 21, 2026
Zone 1
Major retail centers, office parks, and industrial flex. Desert Ridge Marketplace and the 51 corridor received direct impact. Large flat-roof commercial assets in this zone face elevated moisture intrusion risk.
Zone 2
High-density retail and office strip received some of the heaviest hail. The Peoria corridor, including properties along Thunderbird Road, is a direct impact zone.
Zone 3
Retail strip centers, medical office, and mixed-use commercial along Bell Road and 59th Avenue sustained hail exposure.
Zone 4
Commercial office and industrial assets in North Mountain sustained hail exposure. Properties along Bethany Home Road near 19th Avenue are in the confirmed storm path.
Hail damage on flat commercial roofs is frequently invisible from ground level. TPO, EPDM, modified bitumen, and coated roof systems can sustain significant membrane impact damage that does not manifest as leaks for weeks or months.
Scope disputes are the norm on commercial hail claims. Metal flashings, HVAC curbs, rooftop equipment, skylights, perimeter coping, and facades are routinely omitted from initial carrier estimates.
ACV vs. RCV is a critical issue on commercial roofs. Depreciation on a large commercial roof can result in six-figure differences in initial payment.
Arizona storm claims are time-sensitive. Arizona statutes impose proof of loss deadlines. Acting quickly — with professional documentation — protects your claim rights.
The Investigative Standard
We do not accept a carrier's scope as the final word. We approach every commercial claim the way an investigative team approaches a case.
Step 01
Every roofing system, every penetration, every flashing — documented before the carrier scope is accepted.
Carrier adjusters routinely miss scope on complex commercial roof systems. We inspect independently, with measurement and photography.
Step 02
Coverage grants, exclusions, conditions, and valuation clauses — read line by line.
ACV vs. RCV, ordinance & law, coinsurance, and deductible structures each affect claim value. We identify coverage the carrier may not volunteer.
Step 03
Distinguishing storm damage from wear, age, and pre-existing conditions.
Ambiguous causation is the most common tool carriers use to reduce or deny commercial claims. We counter it with documentation.
Step 04
A professionally prepared damage scope and cost estimate — not the carrier's.
Our estimate reflects current contractor pricing, local code requirements, and proper material specifications. It is evidence, not a starting bid.
Step 05
Identifying and documenting items omitted from the carrier's initial estimate.
Most commercial claims settle higher with documented supplemental submissions. We prepare and present those submissions with the evidence to support each line item.
Step 06
Umpire coordination, evidence packaging, and competing estimate analysis.
When carrier and policyholder cannot agree, appraisal is a contractual right under most commercial property policies. We prepare for it from day one.
Your Adjusters
Licensed public adjusters working exclusively on behalf of policyholders — not carriers, not agents, not attorneys.
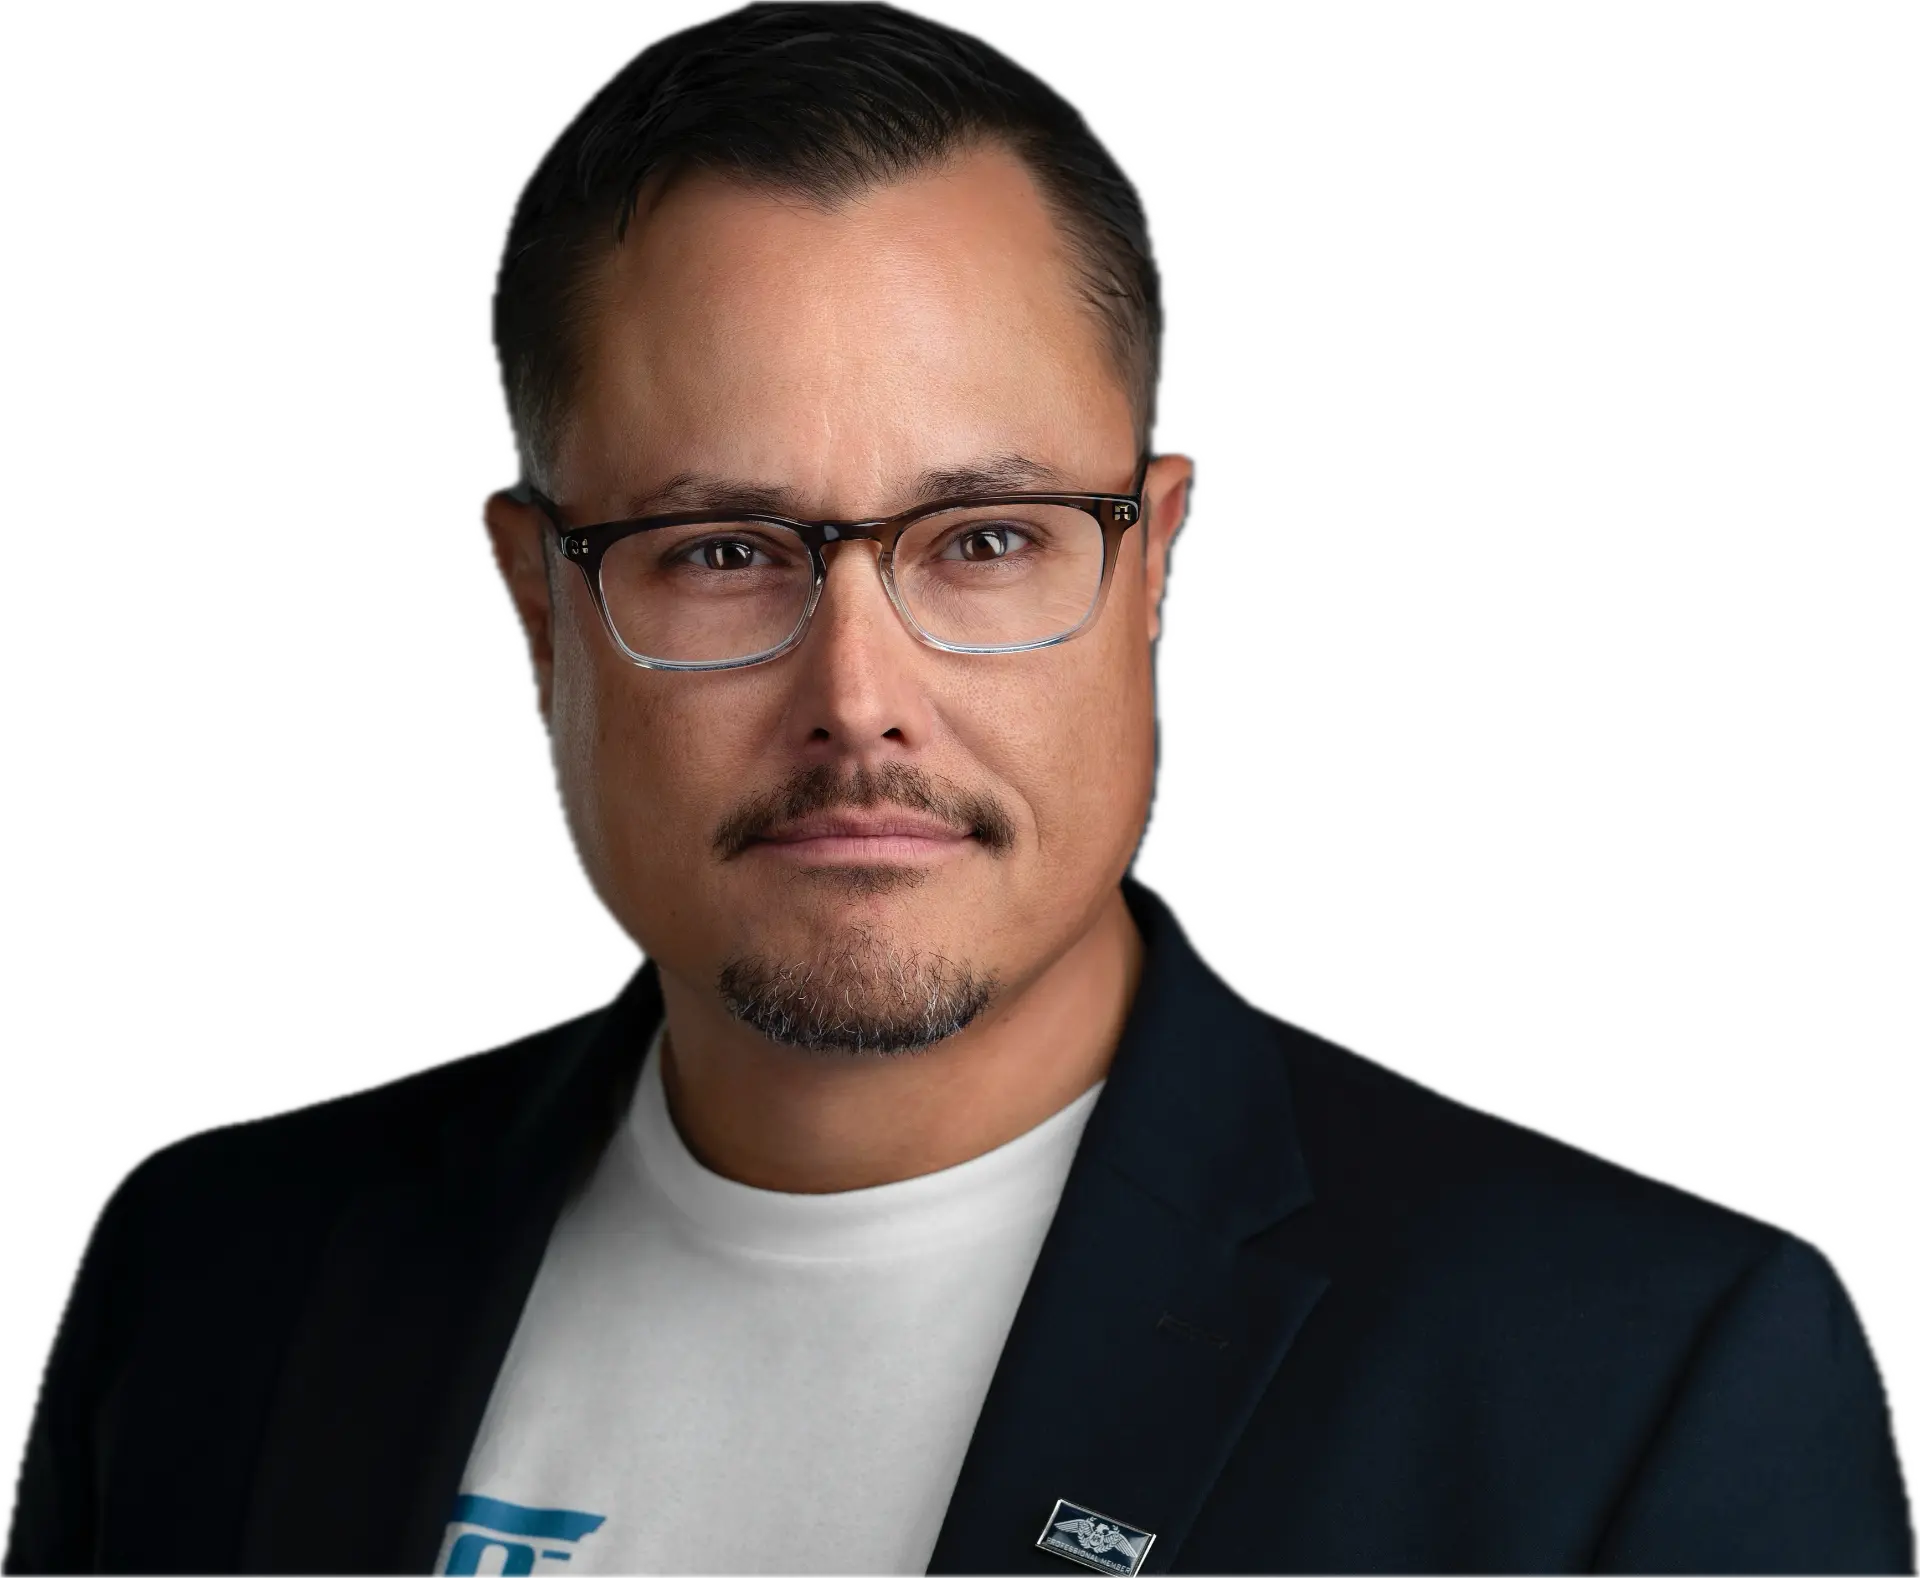
Public Insurance Adjuster
Cameron leads Denali's commercial property practice, specializing in large-loss hail, wind, and storm claims across the Phoenix Valley and surrounding Arizona markets. His approach combines meticulous damage documentation with deep knowledge of commercial roofing systems — TPO, EPDM, modified bitumen, metal, and tile — and the policy language that governs them. Licensed and active in Arizona, Colorado, Texas, and Oklahoma, Cameron brings regional market knowledge and consistent standards to every claim regardless of geography.
Cameron has worked catastrophic hurricane and flood claims across Florida and Louisiana — including high-rise and hotel losses — bringing that real-world, large-loss experience to every claim he handles.
With a background in commercial real estate and property management, Cameron brings a portfolio operator's perspective to every claim — understanding what's at stake for owners and managers when a claim outcome falls short.
Licensed PA — Arizona · Colorado · Texas · Oklahoma · Louisiana
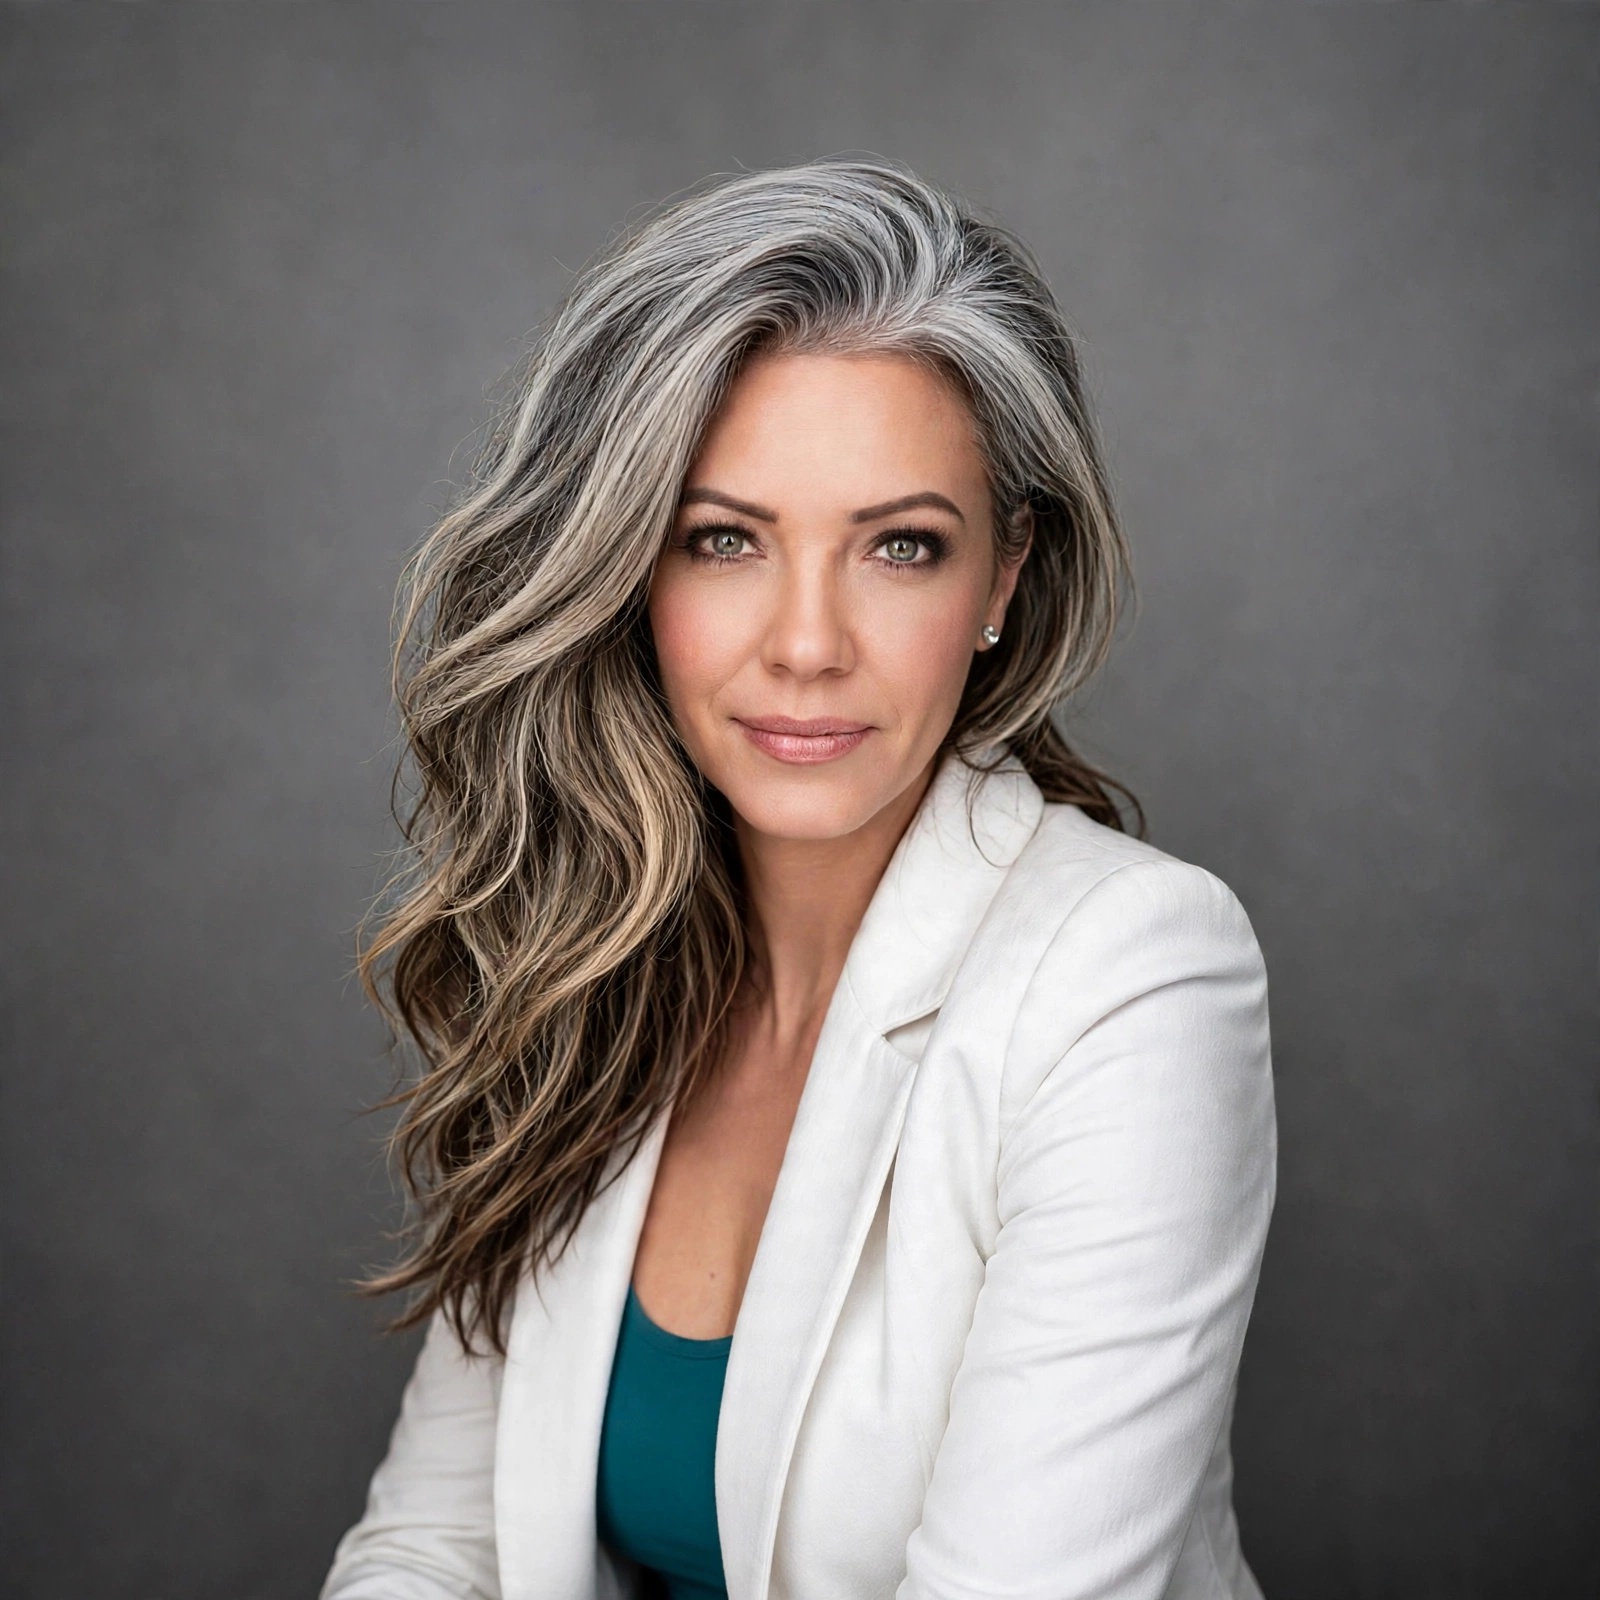
Public Insurance Adjuster
Jules brings precision documentation and client communication expertise to Denali's claims practice. Her focus on policy review, coverage identification, and supplement recovery ensures that no legitimate line item is left on the table in a commercial claim.
Jules has worked catastrophic hurricane and flood claims across Florida and Louisiana — including high-rise and hotel losses — bringing deep catastrophe-response experience to every file.
Jules works directly with property owners and asset managers throughout the claims process — translating complex policy language into clear strategy, and keeping clients informed at every stage from first inspection through final settlement.
Licensed PA — Arizona · Colorado · Texas · Oklahoma · Louisiana
Together, Cameron and Jules have worked hurricanes and floods across Florida and Louisiana — assisting in bringing hundreds of millions of dollars in recovered funds back to the policyholder.
Whether it's a fire or a hurricane, a high-rise or a hotel — we have the real-world claims experience to handle your claim.
"Insurance companies have teams of adjusters, engineers, and attorneys whose full-time job is claim management. The commercial policyholder who faces that team alone is starting from a structural disadvantage. Our job is to close that gap."
Expert Consulting
Denali Loss Consulting provides independent technical consulting, expert file review, and appraisal support for attorneys handling property insurance coverage disputes, bad faith litigation, and construction defect matters.
Curriculum Vitae
Public Insurance Adjuster | Commercial Roofing & Building Envelope Consultant
Licensed public insurance adjuster and commercial roofing/building envelope professional with approximately 23 years of experience in roofing, restoration, construction operations, technical roof assessments, and property insurance claims. Available for independent technical consulting, claim evaluation, appraisal assignments, and expert support within applicable professional and licensing boundaries.
"Evidence-driven, objective assessments that distinguish observed facts from opinions; transparent assumptions and limitations; technically supportable conclusions; and a commitment to fair claim evaluation."
No engineering or architectural licensure is claimed.
TPO, PVC, EPDM, modified bitumen, built-up roofing, ballasted systems, and recover/retrofit evaluations
Composition shingles, concrete/clay tile, synthetic tile, metal roofing, and repairability considerations
Wind, hail, water intrusion, age-related deterioration, workmanship deficiencies; differentiation of observed conditions and causation hypotheses
Published specifications, installation details, technical bulletins, and warranty-related assembly requirements
Photographic inspections, roof condition reports, scope narratives, quantity takeoffs, repair specifications, and Xactimate-based estimate development
Testimony or formal expert opinions are subject to case-specific qualification, review, and engagement agreement.
Contact us to discuss your matter, confirm current availability, and request a full CV and credentials package.
Licensed & Active
Nationwide Response Available
Phoenix Valley · Glendale · Peoria · Scottsdale · Mesa · Tucson & statewide
Denver · Colorado Springs · Aurora · Fort Collins & statewide
Dallas · Houston · Fort Worth · Austin · San Antonio & statewide
Oklahoma City · Tulsa · Norman · Broken Arrow & statewide
Get Started
If your commercial property sustained exposure in the October 21, 2026 Phoenix Valley hailstorm — or if you have an existing claim you believe came back short — contact Denali Loss Consulting today. We review your damage, your policy, and your options. No obligation.
Arizona|Colorado|Texas|Oklahoma|Nationwide Response Available|No Recovery, No Fee
Arizona • Colorado • Texas • Oklahoma • Available nationwide for commercial, industrial & multifamily claims
CONFIDENTIAL — DENALI LOSS CONSULTING. Not for distribution to insurance carriers, their counsel, or their representatives. This material contains research findings and professional assessments prepared for commercial property owner and asset manager education. It does not constitute legal advice, coverage opinion, or a guarantee of any specific claim outcome. Denali Loss Consulting is a licensed public adjusting firm.